TL;DR
Expats often own assets and owe debts in several currencies at once. The correct method is to choose one base currency, convert every current asset and liability using rates from the same date, and review foreign pensions and property separately for tax and liquidity risks. Currency movement can change your reported net worth even when the underlying asset has not changed in local terms.
Why Standard Net Worth Tracking Gets Harder for Expats
A domestic balance sheet is usually measured in one currency. Your savings, mortgage, retirement plan and investments may all be stated in dollars, pounds or euros.
An expat financial life can be very different.
Imagine a U.S. citizen living in Germany with a euro-denominated home and mortgage, a U.S. brokerage account in dollars, a workplace pension from the United Kingdom in pounds and emergency savings in UAE dirhams. Each item belongs in net worth, but the balances cannot be added together until they are expressed in the same currency.
The formula does not change:
Net Worth = Total Assets − Total Liabilities
The work lies in normalising the inputs. A €400,000 apartment and a €240,000 mortgage may show €160,000 of equity locally. But the value of that equity in dollars, pounds or dirhams changes as exchange rates move.
For expats, net worth is affected by two forces: the value of each asset or debt in its local currency and the currency conversion used to report the total.
Step 1: Choose One Base Currency
Start by choosing the currency in which you want to measure your financial position.
For some expats, the obvious choice is the currency used for current living costs. Someone living permanently in Germany may choose euros because rent, food, taxes and retirement spending are expected in euros.
For others, the better base is the currency of the country where they expect to retire. An expatriate currently earning in dirhams but planning to retire in the United Kingdom may prefer pounds because long-term spending will likely be measured in pounds.
Your passport country is not automatically the right answer. Choose the currency connected to your most important future goal.
Then convert every asset and liability into that base currency using exchange rates from the same date. Do not use one exchange rate for your savings account and a different date’s rate for your mortgage. That creates a distorted snapshot.
For example, a balance sheet reported in U.S. dollars might include:
| Financial Item | Local Balance | Converted USD Value |
| German property equity | €160,000 | $174,400 |
| UK pension balance | £72,000 | $93,600 |
| UAE savings | AED 90,000 | $24,500 |
| U.S. brokerage account | $85,000 | $85,000 |
| Total Net Worth in USD | $377,500 |
The conversion rates in this example are illustrative only. Your calculation should use current rates on the date of review.
Step 2: Understand How Currency Changes Asset Values
A foreign asset can remain stable in its home country while appearing to rise or fall in your base currency.
Suppose an apartment in Europe remains worth €500,000. When €1 equals $1.10, the property appears on a dollar-based balance sheet at $550,000. If the euro later weakens to $1.00, the same unchanged property appears as $500,000.
Your home did not lose €50,000 of local market value. Your dollar-denominated net worth still fell by $50,000 because the exchange rate changed.
The same applies to foreign debts. A euro mortgage becomes more expensive in dollar terms when the euro strengthens against the dollar. This is especially important when your income and debt are in different currencies.
A useful expat net worth review therefore keeps two views:
- Local-currency value for each major asset and debt.
- Total converted value in your chosen base currency.
This helps you separate genuine investment or property changes from currency movement alone.
Step 3: Track Foreign Cash and Savings Consistently
Cash held across countries can become difficult to monitor because balances are often scattered across current accounts, savings accounts and digital wallets.
List every cash balance in its original currency, then convert it on your review date. A monthly review may be useful when you frequently save or spend in several currencies. A quarterly review may be sufficient when balances are stable and you do not want normal exchange-rate movement to distract from long-term progress.
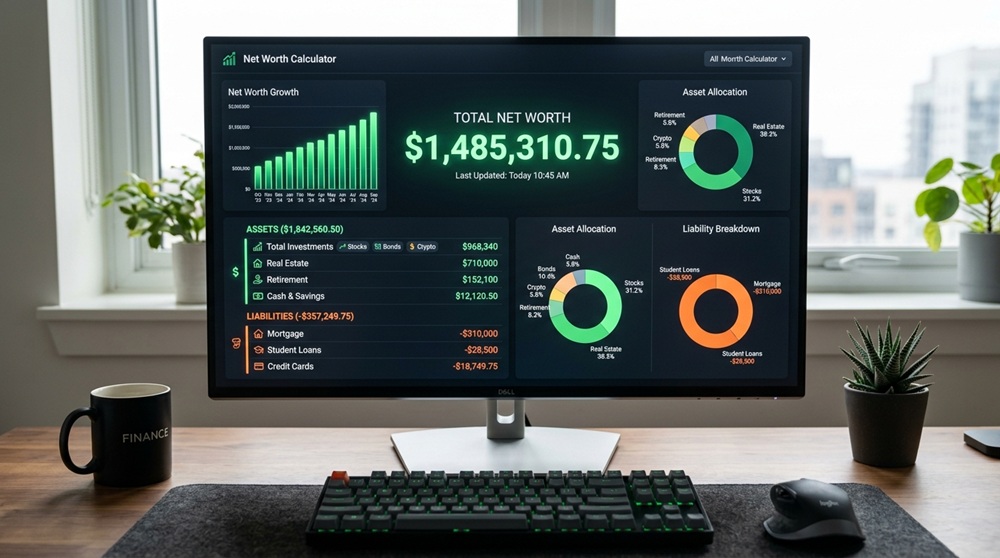
A multi-currency net worth calculator can make the reporting step easier by letting you view your balance sheet in a selected currency and converting entered values using a daily reference exchange rate. This is useful for comparing your total financial position in currencies such as USD, EUR, GBP, AED, TRY, PKR and several others without manually rebuilding the entire snapshot each time.
Keep one limitation in mind: a currency conversion produces a current reporting value. It does not eliminate currency risk or tell you which currency is best for your future needs.
Step 4: Handle Foreign Pensions and Tax Wrappers Carefully
Foreign pensions and investment accounts belong in net worth when you own a measurable interest in them. The difficult part is estimating what they may eventually provide after taxes.
A United Kingdom Individual Savings Account, or ISA, can hold savings and investments tax-free under UK rules. That does not mean another country where you now live or file taxes will automatically treat it the same way. A foreign tax authority may apply different rules.
The same issue arises with pension arrangements in Germany, France, the UAE or elsewhere. A plan may be tax-favoured in the country where it was created while receiving different treatment in your new country of residence or under citizenship-based tax rules.
For example, the IRS states that income from foreign pensions or annuities may be fully or partly taxable in the United States. It also states that tax-treaty benefits vary by country and by type of income.
For standard net worth tracking, enter the current pension or investment balance when it can be valued. For retirement planning, create a separate note for possible future tax treatment, withdrawal restrictions and currency exposure. Cross-border retirement accounts are one area where advice from a qualified international tax professional can prevent expensive mistakes.
Step 5: Value Foreign Property in Local Terms First
Property owned abroad should be valued using current local-market evidence, not the original purchase price converted into your preferred currency.
Start with comparable sales, a professional valuation or a conservative local estimate. Subtract any mortgage or property-secured loan in the same local currency to calculate local equity. Only then convert the equity into your base currency.
For example:
Current Property Value: €420,000
Remaining Mortgage: €255,000
Local Home Equity: €165,000
Convert that €165,000 equity into your reporting currency on the review date.
Do not assume a standard 6% to 10% sale cost applies in every country. Agent fees, transfer taxes, legal fees, capital-gains rules, foreign-owner restrictions and rules governing the transfer of sale proceeds vary widely by jurisdiction. These costs may not belong in your routine monthly calculation, but they matter when you are planning to sell, relocate or use the property to fund retirement.
Step 6: Manage Currency Volatility Without Obsessing Over It
Exchange-rate movement can make net worth appear unstable, especially when most of your wealth is held in a different currency from the one used for reporting.
Do not react to every monthly FX fluctuation as though your long-term plan has failed. Instead, choose a review policy.
Track day-to-day spending and short-term cash needs in the currency where those bills occur. Review full converted net worth monthly or quarterly using one consistent base currency. For large assets such as foreign property or pensions, note both the local value and converted value so you can identify whether a change comes from the asset itself or from foreign exchange.
The right answer is not to ignore currency risk. It is to measure it in a way that supports decisions rather than creating noise.
For more practical resources on assets, liabilities and personal financial tracking, visit NetlyWorth.
Your Net Worth Is Manageable Once Every Currency Has a Place
Living internationally can make your finances look more complicated than they are. You still own assets, owe liabilities and need one reliable number showing where you stand.
Choose a base currency connected to your future plans. Convert all balances on the same date. Track foreign property, pensions and taxes with care. Review currency movement without confusing it with investment progress. With a consistent method, an international balance sheet becomes clear enough to guide saving, investing and retirement decisions wherever life takes you.